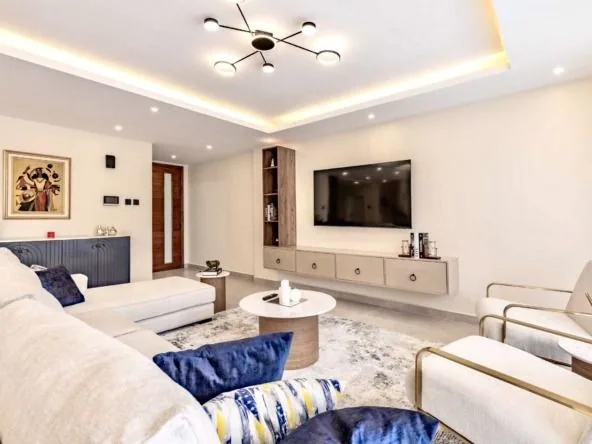
Buying a home is perhaps one of the biggest financial decisions most Kenyans will ever make. The median home value in Kenya, according to the Kenya Bankers Association, varies from KSh 10 million up to KSh 20 million, depending on location and the type of property. Most people don’t just have this amount in handy cash, and hence, a mortgage may be required in the home-buying process.
Here are the key steps to ensure you get the best mortgage offers possible:
1. Deposit a Substantial Down Payment
A larger down payment is one of the best ways to get a lower mortgage rate. The more you pay upfront, the better the interest rates and the smaller the loan you need. The decision to spend more on the down payment needs to be considered concomitantly with possible returns from other investments. Determine if reducing monthly mortgage repayments benefits you more than investing that money.
2. Compare Rates from Different Banks & Lenders
Homebuyers often don’t shop around to get the best mortgage rates. Make sure to get the most competitive offer: research bank rates from major banks such as KCB, Equity, Absa, Co-op Bank, NCBA, Stanbic, Housing Finance Limited, and I&M Bank. Compare mortgage prices using mortgage comparison tools such as the Kenya Bankers Association (KBA) Housing Price Index. Additionally, explore SACCOs and microfinance institutions, which might give you better rates than a bank. Mortgage rates are influenced by the Central Bank Rate (CBR) and the Kenya Bank’s Reference Rate (KBRR). Check on both Rates. A lower CBR rate means you can get lower mortgage rates. Choose between fixed or variable interest rates. Fixed rates do not change, therefore providing stability, whereas variable rates can begin lower but can change following market conditions. Consider the loan tenure. The longer the repayment period (up to 25 years), the lower the monthly payment, but the higher the total interest paid, and vice versa.
3. Check if the prices include other costs and ask the right questions.
Always know what the current interest rate is for the mortgage you are considering and what future rate expectations are. Before committing to a lender, ask them critical questions regarding possible rate variations and make sure you know all associated costs, for example: Processing fees, Insurance charges, Property valuation fees, and Legal fees. However, some lenders who offer low interest rates may cushion these with high additional costs, so it is important to weigh the total cost of borrowing.
4. Seek Expert Advice
We suggest you consult a housing finance provider or use mortgage calculators on Kenyan real estate websites to determine what you can afford given your income and expenses. Financial experts can help you pick the right mortgage product that fits your long-term financial objectives.
5. Borrow Within Your Means
Rapidly rising Kenyan property prices mean homebuyers will mostly find mortgage repayments increase beyond rental costs. You probably won’t be able to pay your mortgage entirely with rental income unless you supplement it with income from other sources. Make sure your monthly payments on your mortgage are something you can afford to do now and won’t weigh heavily on your purse strings later on.
Conclusion
Understanding the challenges of locating and buying homes is important. By saving for a larger down payment, comparing mortgage offers, asking critical questions, seeking expert advice, and borrowing responsibly, you can secure the best mortgage rates in Kenya and realize your dream of homeownership.